What changed in September 2026
For years, plenty of Texas homeowners got a nonrenewal letter that boiled the reason down to one line: the roof is too old. It didn't matter if the roof was holding up fine. In August 2026, Governor Abbott directed the Texas Department of Insurance to look into rising property insurance costs across the state. A month later, TDI issued a clarification: insurers cannot deny or refuse to renew a homeowners policy based solely on the age of the roof or the home. Age by itself is off the table as a reason.
That clarification lines up with a separate Texas law that took effect in 2025, which requires insurers to give homeowners a specific written reason any time they decline, cancel, or decide not to renew a policy, with that reporting to TDI starting in April 2026. Together, the two rules mean you're entitled to a real answer, and "your roof is old" alone is no longer a valid one.
Age versus condition: what insurers can still use against you
This isn't a blanket protection for every aging roof. Insurers are still allowed to consider the roof's actual condition, and condition is where most real denials will keep happening. That includes things like:
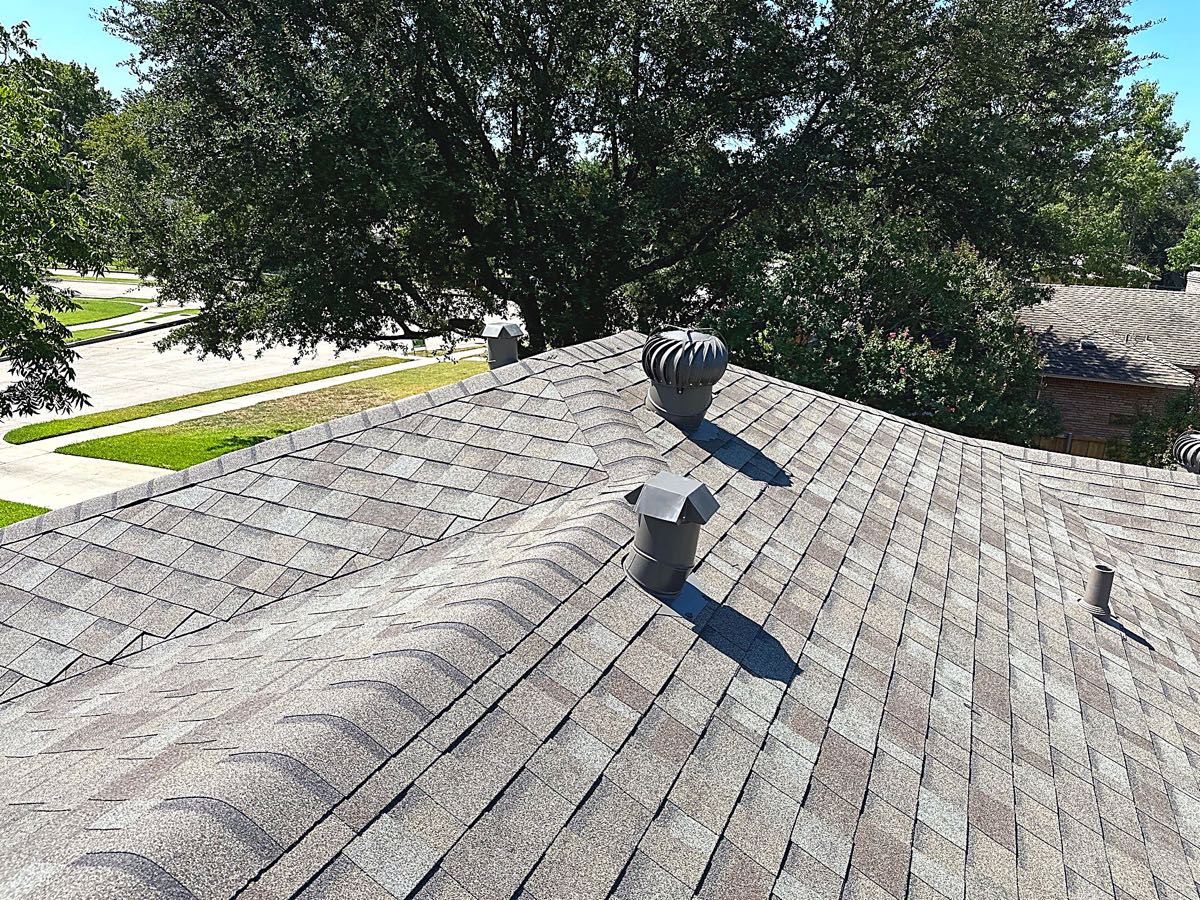
- Missing, curling, or cracked shingles visible from the ground or a drone inspection
- Granule loss heavy enough to expose the underlying mat
- Storm damage from a prior hail or wind event that was never repaired
- Sagging decking, moss growth, or other signs of a leak that's been ignored
A 20-year-old roof that's been maintained and shows no real wear is a different risk than a 20-year-old roof that's falling apart. The new rule just means the insurer has to point to the second kind, not the calendar, if they want to act.
Why your policy type still matters if a storm hits that old roof
Keeping your policy and getting paid fully if something happens to the roof are two different questions. Even with the September 2026 rule in place, your coverage type still decides how a claim pays out. Actual Cash Value policies factor in depreciation, so an older roof gets a smaller check after a covered loss. Replacement Cost Value policies pay to replace it regardless of age. If you're not sure which one you have, our guide to ACV vs. RCV on a Texas roof claim walks through how to check your own policy and what the difference is worth in dollars.
What to do if you get a nonrenewal or decline notice
- Ask for the specific written reason. Texas law now requires it. If the letter just says "roof age," ask them to put the actual basis in writing.
- Point to the September 2026 TDI clarification if age is the only reason given, and ask the insurer to reconsider based on your roof's real condition.
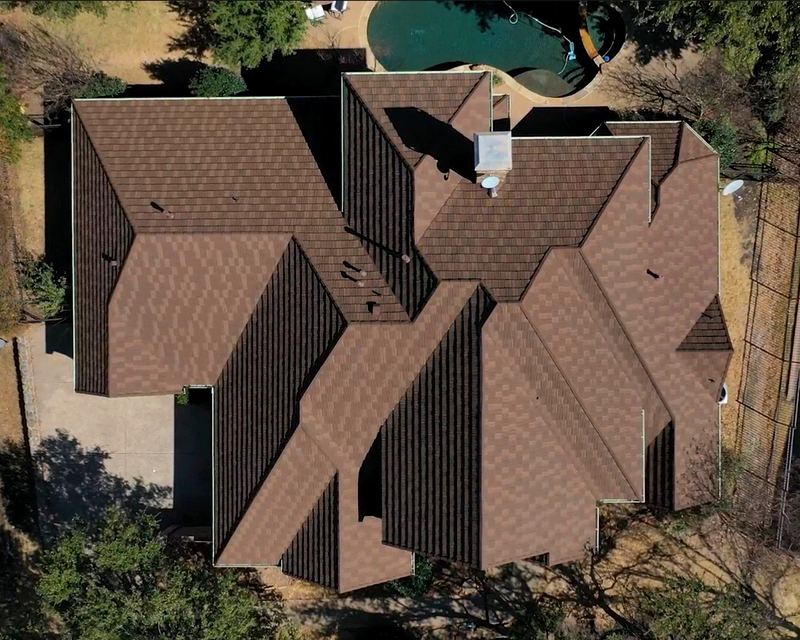
- Get a free, documented roof inspection. Photos and a written assessment from a licensed roofer give you current proof of condition instead of letting the insurer guess from a satellite image.
- If the roof genuinely needs work, get it done. A roof replacement or targeted repair can resolve the condition issue the insurer actually cares about.
- Call the Texas Department of Insurance Help Line if you believe the denial is still improper after you've pushed back.
- Shop around. Not every carrier treats the same roof the same way, and a fresh inspection report helps with a new application too.
A documented inspection protects you either way
Whether you're trying to keep your current policy or you need a clean report to shop for a new one, the same step helps: a real, documented look at your roof's condition from someone who isn't guessing from the street. We serve homeowners across Garland and the rest of DFW, and if your roof took hail or wind damage at some point that you never got around to filing, our storm damage team can tell you whether that's still worth a claim before it becomes the "condition" reason an insurer points to later.
Bottom line
Roof age alone can't get your Texas homeowners policy declined or dropped anymore, but a genuinely worn or damaged roof still can. The smartest move either way is the same one: know your roof's real condition before your insurer tells you what they think it is. A free inspection settles that question in about thirty minutes.